How Credit Cards Work: APR, Fees and US Protections
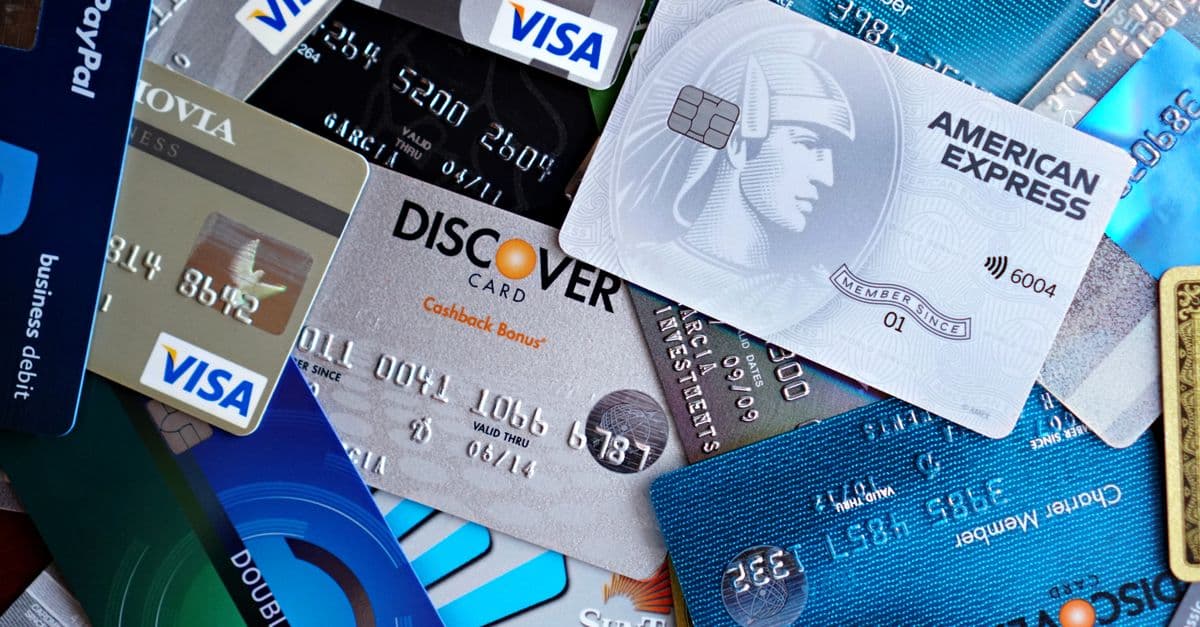
Photo: DΛVΞ GΛRCIΛ / Pexels
A credit card combines a payment service with a borrowing agreement. The payment can take seconds, while repayment, interest, and disputes follow a much longer timetable. Understanding that separation explains why an approved purchase is not free money, why a promotional rate is not the same as deferred interest, and why both credit and debit cards have legal protections. This overview focuses on US consumer cards; contracts and protections in other jurisdictions can differ.
Educational information, not financial or legal advice. Examples are hypothetical, not current product offers or recommendations for an individual's finances.
Correction — October 15, 2026: We corrected debit-card fraud protections, the distinction between zero-percent APR and deferred interest, and bankruptcy-reporting language. We removed unsupported product rates, guaranteed secured-card graduation, precise credit-score effects, and generalized recommendations.
What happens between a purchase and a bill
In a common four-party card arrangement, the participants are the cardholder, merchant, issuing bank, and merchant's acquiring bank. A network connects the institutions. The issuer posts a charge to the cardholder's account, while the acquirer credits the merchant under its agreement. Other arrangements combine some of those roles. Federal Reserve explanation of payment-card networks.
Interchange is a payment between the acquiring and issuing sides of that system. It is not necessarily the entire fee deducted from the merchant's proceeds. The merchant's overall acceptance cost can include other charges, so a universal percentage cannot describe every transaction. Federal Reserve explanation.
The network is like a delivery route for payment instructions; the issuer's credit agreement determines the borrower's obligations. Confusing those functions can make a card logo seem to determine terms that actually depend on the account. The same purchase amount can therefore lead to different borrowing costs under different agreements.
Why the grace period has conditions
A grace period is the interval between the close of a billing cycle and the payment due date. US issuers are not required to offer one, although most cards provide a grace period for purchases. When an account qualifies, paying the required balance in full by the due date can avoid purchase interest. CFPB grace-period explanation.
Carrying a balance can remove that protection. Interest can then apply to the unpaid balance and to new purchases from their transaction dates. Cash advances generally do not receive the purchase grace period. The agreement determines the conditions for regaining it; there is no universal promise that one payment immediately restores every account's grace period. CFPB guidance.
Think of the statement as a photograph at the billing-cycle close, while the current balance is a moving picture. Purchases and payments after the photograph can change the current balance. Those dates help explain why the statement amount, outstanding balance, and amount needed to eliminate interest are not always interchangeable.
How APR becomes an interest charge
APR means annual percentage rate. Different APRs may apply to purchases, cash advances, and other balance categories on the same account. Many issuers calculate interest using daily balances, which means the timing of transactions and payments matters. CFPB interest calculation explanation.
For an explicitly hypothetical illustration, an APR of 24% divided by 365 is approximately 0.06575% per day. Applied to a hypothetical unchanged $1,000 balance, that is about $0.66 for one day before considering the account's other terms. This is arithmetic showing a daily-rate calculation, not a quoted offer or a monthly payoff estimate. CFPB contract definitions.
Daily accrual does not mean every card compounds interest identically. The CFPB's definitions distinguish daily and average-daily-balance methods with and without compounding. An account's disclosed calculation method matters more than the blanket assertion that every card compounds daily. For related mathematics, see compound interest explained. For broader context, see why interest rates affect everything.
What a minimum payment does and does not mean
The minimum payment is the amount required under the account's terms for that billing period. It is not a promise that the debt will disappear quickly. Paying only the minimum can leave a balance outstanding for years, depending on interest, fees, the payment formula, and additional charges. CFPB minimum-payment explanation.
A statement's three-year repayment illustration assumes no additional purchases and the specified payments. It is not a forecast that still holds after new borrowing. A precise payoff calculation needs a defined starting balance, rate, fees, payment schedule, and assumptions about future charges. CFPB statement explanation.
Zero-percent APR is different from deferred interest
A genuine zero-percent APR promotion does not accrue interest attributable to its zero-rate period. When that promotion expires, the applicable rate can begin to apply to the remaining unpaid balance. It does not automatically recreate interest on the original transferred amount for the earlier zero-rate months. Transfer fees and other conditions still matter. Regulation Z distinction.
For a hypothetical example, suppose a $1,000 promotional balance has been reduced to $200 when a genuine zero-rate period ends. The remaining $200, rather than the original $1,000, is the relevant unpaid principal going forward, subject to the agreement. This simplified example excludes fees, new purchases, and other balance categories.
A deferred-interest offer is different: wording such as “no interest if paid in full” can mean accrued interest is charged if the qualifying balance is not fully repaid by the deadline. Minimum payments may not retire the balance before that deadline. The phrase “interest-free” alone is therefore insufficient to establish how an offer works. CFPB deferred-interest explanation.
Both credit and debit cards have fraud protections
US credit-card law limits liability for unauthorized use, generally to a maximum of $50; reporting a lost or stolen card before unauthorized use can avoid liability for subsequent charges. Issuer policies may provide additional protection. This is distinct from the procedures for disputing a billing error. FTC credit-card protection explanation and card-type comparison.
Debit cards also have federal protections. For a lost or stolen debit card, reporting within two business days of discovering the loss generally limits liability to $50; later reporting can raise exposure to $500. Failure to report an unauthorized transfer within 60 days after the statement is sent can create additional liability for later transfers under specified conditions. CFPB debit-transaction explanation.
The details differ when an unauthorized transaction occurs without loss of the physical card. Investigation and provisional-credit rules also matter. It is inaccurate to describe debit cards as lacking fraud protection or to turn one reporting deadline into a universal rule covering every credit and debit dispute. CFPB explanation.
What secured cards and bankruptcy do not guarantee
A secured credit card generally requires a deposit that backs the credit line. It is still borrowing: the deposit does not replace the obligation to make payments. This differs from spending money already loaded onto a prepaid card. FTC comparison of card types.
A secured card may help establish credit history, but fees, reporting practices, and eligibility vary. There is no universal guarantee of conversion to an unsecured card after six or 12 months. Repayment history and other factors affect creditworthiness; a particular score increase cannot be promised. CFPB rebuilding-credit explanation. See also how credit scores estimate risk.
Bankruptcy is a legal process with consequences that cannot be reduced to a guaranteed period of financial devastation. Generally, bankruptcy information can remain on a US credit report for up to 10 years; exceptions can apply. That reporting period is not a fixed prediction of one person's score or recovery. CFPB bankruptcy-reporting explanation.
The takeaway
The useful unit of comparison is the credit agreement, not the appearance of the card or the size of an advertised reward. Grace periods, balance categories, promotional language, fees, and dispute procedures answer different questions. A zero-rate balance transfer is not a deferred-interest purchase, and debit protection is not the absence of protection. Understanding those distinctions makes borrowing costs and legal rights easier to assess without promising that one product suits everyone.
Follow new articles
Add SciHub101 to your feed reader to see new science and technology stories.
About the Author
SciHub101 is an independent science and technology publication founded and edited by Buğra Sözeri, a software engineer and app developer based in Türkiye. AI tools assist with drafting and research. Source documentation in the existing archive is uneven, and articles are being reviewed and corrected. The Editorial Team byline identifies editorial responsibility; it does not certify specialist or independent human review. Where we compare products, anything built by our own team is labelled as such — see the editorial guidelines and About page for how corrections and disclosures work.
Related Articles
Index Funds vs Active Funds — Which Wins?
Index funds vs active funds: S&P SPIVA data on 20-year results, fee gaps, the Sharpe arithmetic, and where active management can still make sense.
Yield Curve Inversion Explained — Recession Signal
Yield curve inversion explained: why it's predicted every US recession since 1969, the 2s/10s spread, and whether the signal is breaking down.
Personal Finance Basics — Money Management 101
Build wealth with the fundamentals: emergency fund, budget, debt payoff, retirement accounts, index funds, insurance, and credit. Evidence-based guide.
How to Build an Emergency Fund: A Step-by-Step Framework
An emergency fund is savings set aside specifically to cover unexpected expenses or income loss: a car repair, medical bill, or job layoff. Financial experts generally recommend keeping 3 to 6 months of living expenses in emergency savings. If your monthly expenses are $3,000, that means $9,000 to $18,000 in accessible savings. Most Americans do not have this amount; the Federal Reserve reported that 43 percent of adults could not cover a $400 emergency with cash. Building an emergency fund requires three steps: calculating your monthly expenses, deciding on a target (3, 6, or 9 months), and automating deposits into a separate account until the target is reached. This article explains the mechanics of emergency fund planning, where to keep the funds to balance safety and accessibility, and how to maintain the fund when unexpected expenses occur.
How to Create a Budget Using the 50/30/20 Rule
The 50/30/20 rule is a budgeting framework that divides after-tax income into three categories: 50 percent to needs (essential expenses like rent, food, and utilities), 30 percent to wants (discretionary spending like entertainment and dining out), and 20 percent to savings and debt repayment. If you earn $4,000 per month after taxes, the rule prescribes $2,000 for needs, $1,200 for wants, and $800 for savings and debt. This framework works because it is simple, memorable, and allocates resources to competing priorities in a deliberate way. However, it is not one-size-fits-all: a person with high housing costs (50% of income) or dependents may need to adjust the percentages. This article explains how to implement the 50/30/20 rule, how to categorize expenses, common variations for different life circumstances, and how to track compliance.