personal-finance
24 articles tagged with #personal-finance
Finance & Crypto
How to Build an Emergency Fund: A Step-by-Step Framework
An emergency fund is savings set aside specifically to cover unexpected expenses or income loss: a car repair, medical bill, or job layoff. Financial experts generally recommend keeping 3 to 6 months of living expenses in emergency savings. If your monthly expenses are $3,000, that means $9,000 to $18,000 in accessible savings. Most Americans do not have this amount; the Federal Reserve reported that 43 percent of adults could not cover a $400 emergency with cash. Building an emergency fund requires three steps: calculating your monthly expenses, deciding on a target (3, 6, or 9 months), and automating deposits into a separate account until the target is reached. This article explains the mechanics of emergency fund planning, where to keep the funds to balance safety and accessibility, and how to maintain the fund when unexpected expenses occur.
Finance & Crypto
How to Create a Budget Using the 50/30/20 Rule
The 50/30/20 rule is a budgeting framework that divides after-tax income into three categories: 50 percent to needs (essential expenses like rent, food, and utilities), 30 percent to wants (discretionary spending like entertainment and dining out), and 20 percent to savings and debt repayment. If you earn $4,000 per month after taxes, the rule prescribes $2,000 for needs, $1,200 for wants, and $800 for savings and debt. This framework works because it is simple, memorable, and allocates resources to competing priorities in a deliberate way. However, it is not one-size-fits-all: a person with high housing costs (50% of income) or dependents may need to adjust the percentages. This article explains how to implement the 50/30/20 rule, how to categorize expenses, common variations for different life circumstances, and how to track compliance.
Finance & Crypto
How to Save Money Fast: Evidence-Based Strategies Without Gimmicks
Saving money fast sounds impossible when you live paycheck to paycheck. Yet research on household finances identifies consistent patterns in how people successfully accumulate savings. The most effective strategies are not willpower-based ('spend less') but structural: automating savings so money is removed before you see it, cutting recurring expenses (subscriptions, unused services), and adjusting spending patterns psychologically rather than through restrictive budgeting. A person earning $4,000 per month after taxes can theoretically save $1,000 per month (25%) by cutting unnecessary expenses and automating transfers. Realistically, structural changes (automation, expense cuts) are more sustainable than behavioral willpower. This article examines the evidence-based strategies that work, the psychology of why they work, and realistic expectations for saving speed.
Finance & Crypto
The 4% Rule Explained — Safe Withdrawal Rate
Where the 4% retirement rule came from, what it really says, why critics push 3.25-3.5%, and how Bengen, Trinity, and modern updates compare.
Finance & Crypto
Portfolio Rebalancing — When and How to Rebalance
Rebalancing keeps your portfolio at its target risk. How often to rebalance, threshold vs. calendar methods, tax tricks, and what the research says.
Finance & Crypto
What Is FIRE? Financial Independence Retire Early
What is the FIRE movement? Financial Independence Retire Early explained — 4% rule, savings rates, leanFIRE vs fatFIRE, math, and criticisms.
Finance & Crypto
Dollar-Cost Averaging Explained — Pros and Cons
Dollar-cost averaging (DCA) explained: how it works, when it beats lump-sum investing, the Vanguard research, and the behavioral reasons it still wins.
Finance & Crypto
How Credit Cards Work: APR, Fees and US Protections
How credit cards work: interchange fees, grace periods, APR, promotional offers and secured cards, plus the limits of US consumer fraud protections.
Finance & Crypto
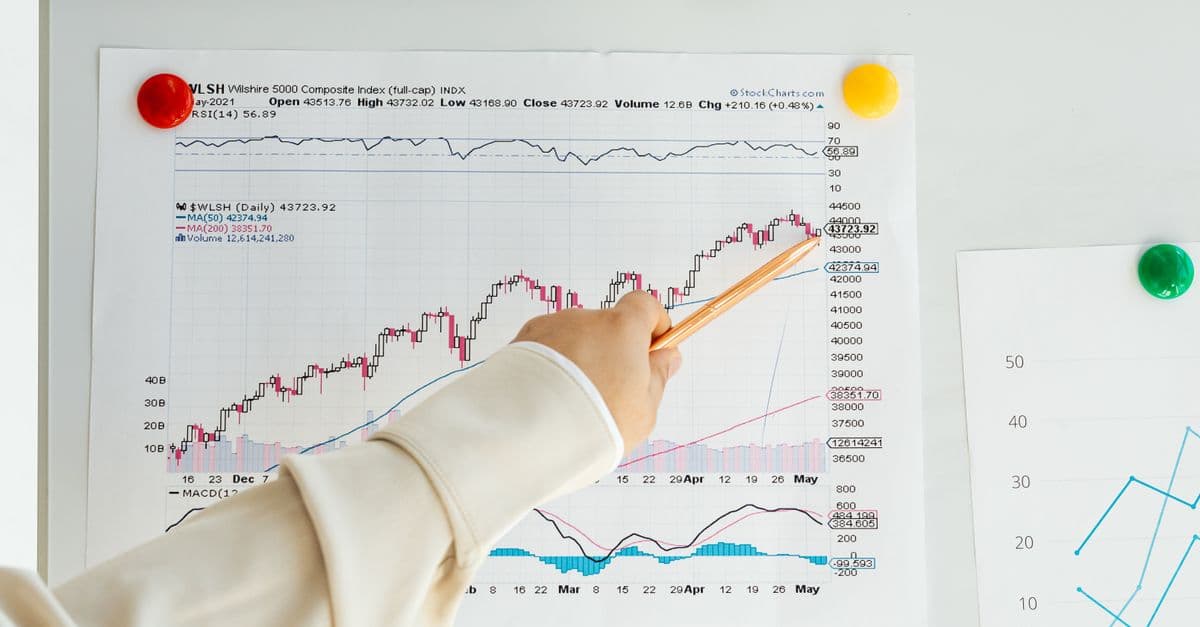
Index Funds vs Active Funds — Which Wins?
Index funds vs active funds: S&P SPIVA data on 20-year results, fee gaps, the Sharpe arithmetic, and where active management can still make sense.
Finance & Crypto
High-Yield Savings Accounts Explained
How HYSAs work, current 4-5% rates, FDIC insurance, and how they compare to CDs, T-bills, and money market funds for parking cash safely.
Finance & Crypto
Personal Finance Basics — Money Management 101
Build wealth with the fundamentals: emergency fund, budget, debt payoff, retirement accounts, index funds, insurance, and credit. Evidence-based guide.
Page 1 of 2Next →